Superannuation for High Earners: A Practical 10-Year Plan
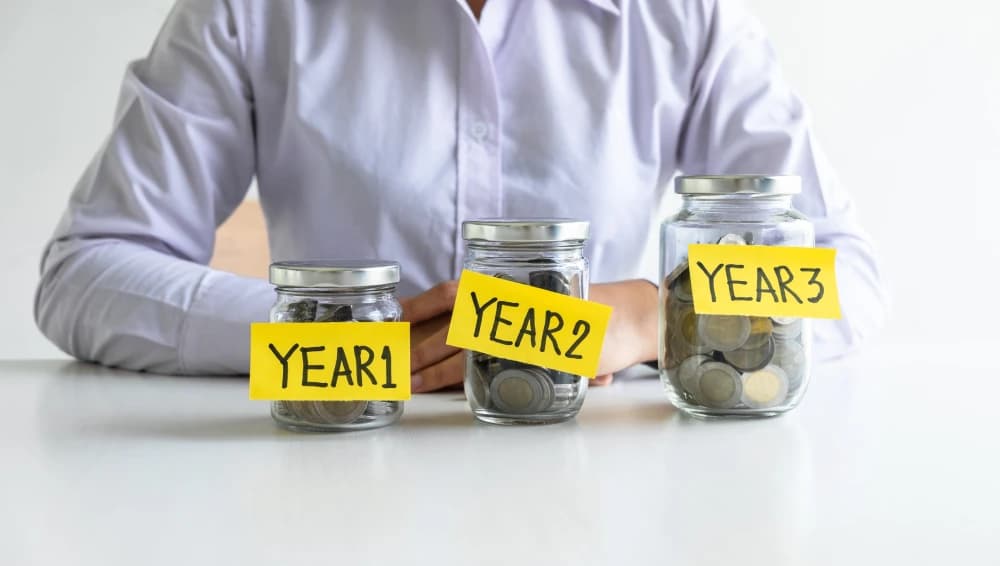
Many high-income professionals leave superannuation in the “later” basket. That’s a costly habit. Super is one of the most powerful after-tax wealth vehicles available in Australia. A clear 10-year plan can do more for your retirement than tinkering at the edges of your portfolio.
This is a practical framework you can follow and review annually.
Year 0: Set the foundation
- Define the goal: What does financial freedom look like for you? (income needed, age, flexibility)
- Map your structures: Employer fund, industry fund, or SMSF (if appropriate).
- Align cashflow: Automate contributions from Day One so progress doesn’t depend on willpower.
Years 1–3: Build momentum
- Use available contribution types (concessional and, where appropriate, non-concessional) within current ATO limits.
- Explore carry-forward opportunities if eligible.
- Review insurance inside super: is it fit for purpose and cost-effective?
- Choose an evidence-based investment mix that you can stick with across cycles (broad, diversified, low-turnover).
Years 4–6: Improve efficiency
- Calibrate contributions with your accountant to manage overall after-tax outcomes (including any additional taxes that may apply to very high incomes).
- Rebalance using new contributions before selling the winners.
- Consolidate any legacy accounts to reduce fees and complexity.
- If your needs warrant it, consider whether an SMSF would add genuine value (control, specific assets) or just complexity.
Years 7–10: Prepare for flexibility
- Model your retirement income (account-based pensions, expected drawdowns, buffers).
- Align your estate plan with beneficiary nominations and your broader legacy plans.
- Stress-test your plan for market shocks and career changes.
- Tighten costs: ensure your chosen fund(s) and platform remain competitive.
The habits that compound the most
- Automate contributions and reviews.
- Ignore short-term noise, your horizon is a decade and beyond.
- Coordinate with your accountant annually; super doesn’t sit in isolation.
- Keep fees and turnover low; let compounding do the heavy lifting.
Common mistakes we see
- Sporadic contributions with no plan.
- Investment choices driven by recent performance rather than a policy.
- Paying for insurance that doesn’t fit (too much, too little, or the wrong definitions).
- Setting up an SMSF for the wrong reasons.
Final word
If you earn well, superannuation is a gift from compounding. A simple 10-year plan reviewed yearly can quietly transform your future.
CTA: Book a 15-minute Clarity Call to map your next decade in super.
General information only. Superannuation rules change—check the current ATO guidance and seek personal advice.
The information on this website is general in nature and does not take into account your personal objectives, financial situation or needs. Before acting on any information you should consider its appropriateness and read the relevant Financial Services Guide.
Want to know how this applies to your situation?
Start with a free 15-minute conversation.
Book a call